🇳🇬 Nigerian investors
UK property investment from Nigeria.
A weaker naira has made sterling property a practical store of value. A guide for Lagos and Abuja professionals and the diaspora: tax, moving funds and buying remotely.
The Property Ombudsman
TPO D14716
ICO Registered
Ref ZB632945
Companies House No. 14716108
Est. England & Wales
Cavendish Square, W1
Central London office
Manchester office
Spinningfields, M1
Why now
Why Nigerian investors are choosing UK property in 2026
For a Nigerian investor, UK property is a store of value in sterling. The naira has fallen sharply against the pound since the 2023 currency reforms, so assets held in sterling have protected purchasing power in a way naira assets have not.
Typical profile: £200k to £800k deployable, often first-time international investors. Lagos-based professionals, UK-educated diaspora, and Nigerians holding USD-denominated savings looking for GBP-denominated assets as a Naira hedge.
- 01
A sterling asset holds its value in naira terms when the naira weakens. That is the main reason Nigerian professionals and families buy in the UK.
- 02
The UK has a large Nigerian community, which supports tenant demand in London, Manchester and Birmingham.
- 03
Education is a common reason to buy. Families with children at UK schools or universities often buy a home near where the children study.
- 04
Dollar savings in a domiciliary account earn little. A let UK property produces rental income in sterling alongside any change in capital value.
Where to buy
The UK cities Nigerian investors most often consider
London
Central and riverside new-build with long leases and no ground rent. Lower yields than the regions, bought mainly for long-term capital value.
London market viewManchester
The largest regional rental market, with a deep city-centre tenant base drawn by finance, media and two major universities.
Manchester market viewBirmingham
The UK's second city, with major regeneration around the city centre and a large young workforce.
Birmingham market viewLive opportunities
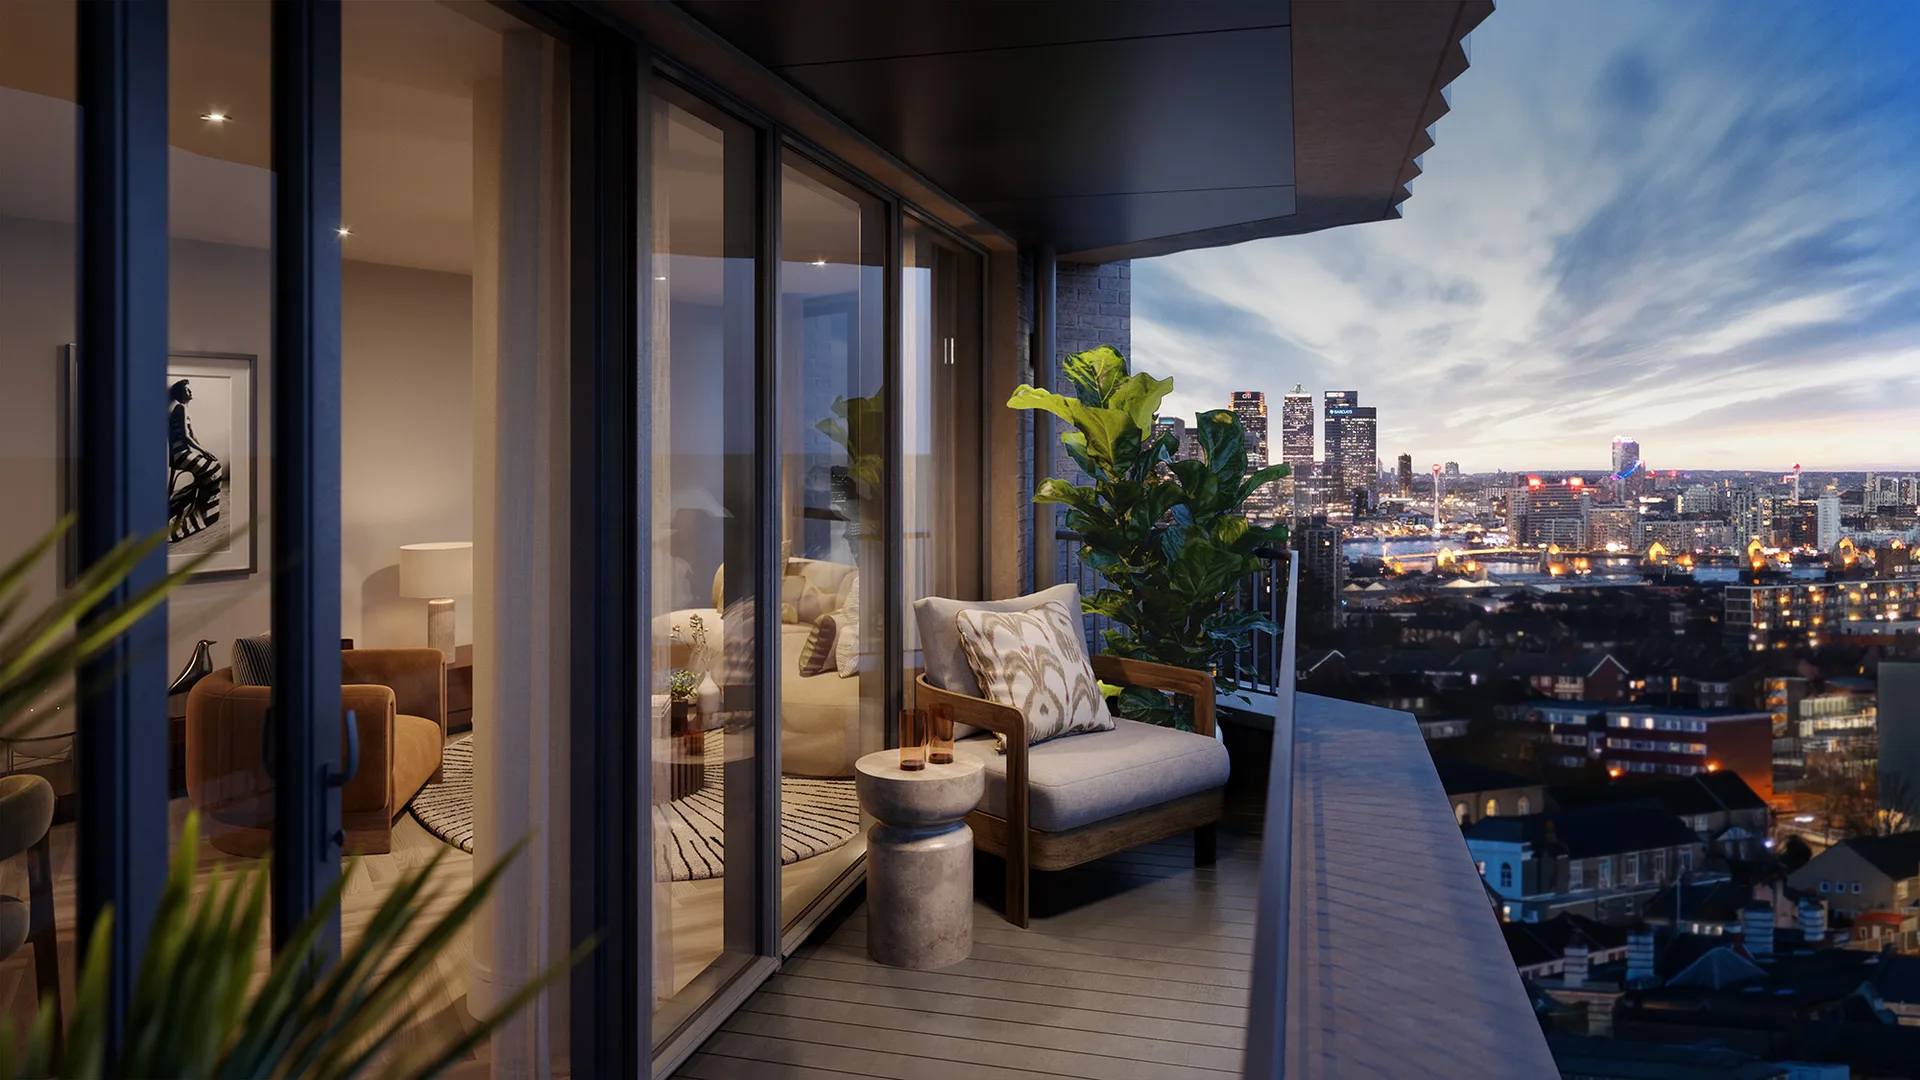
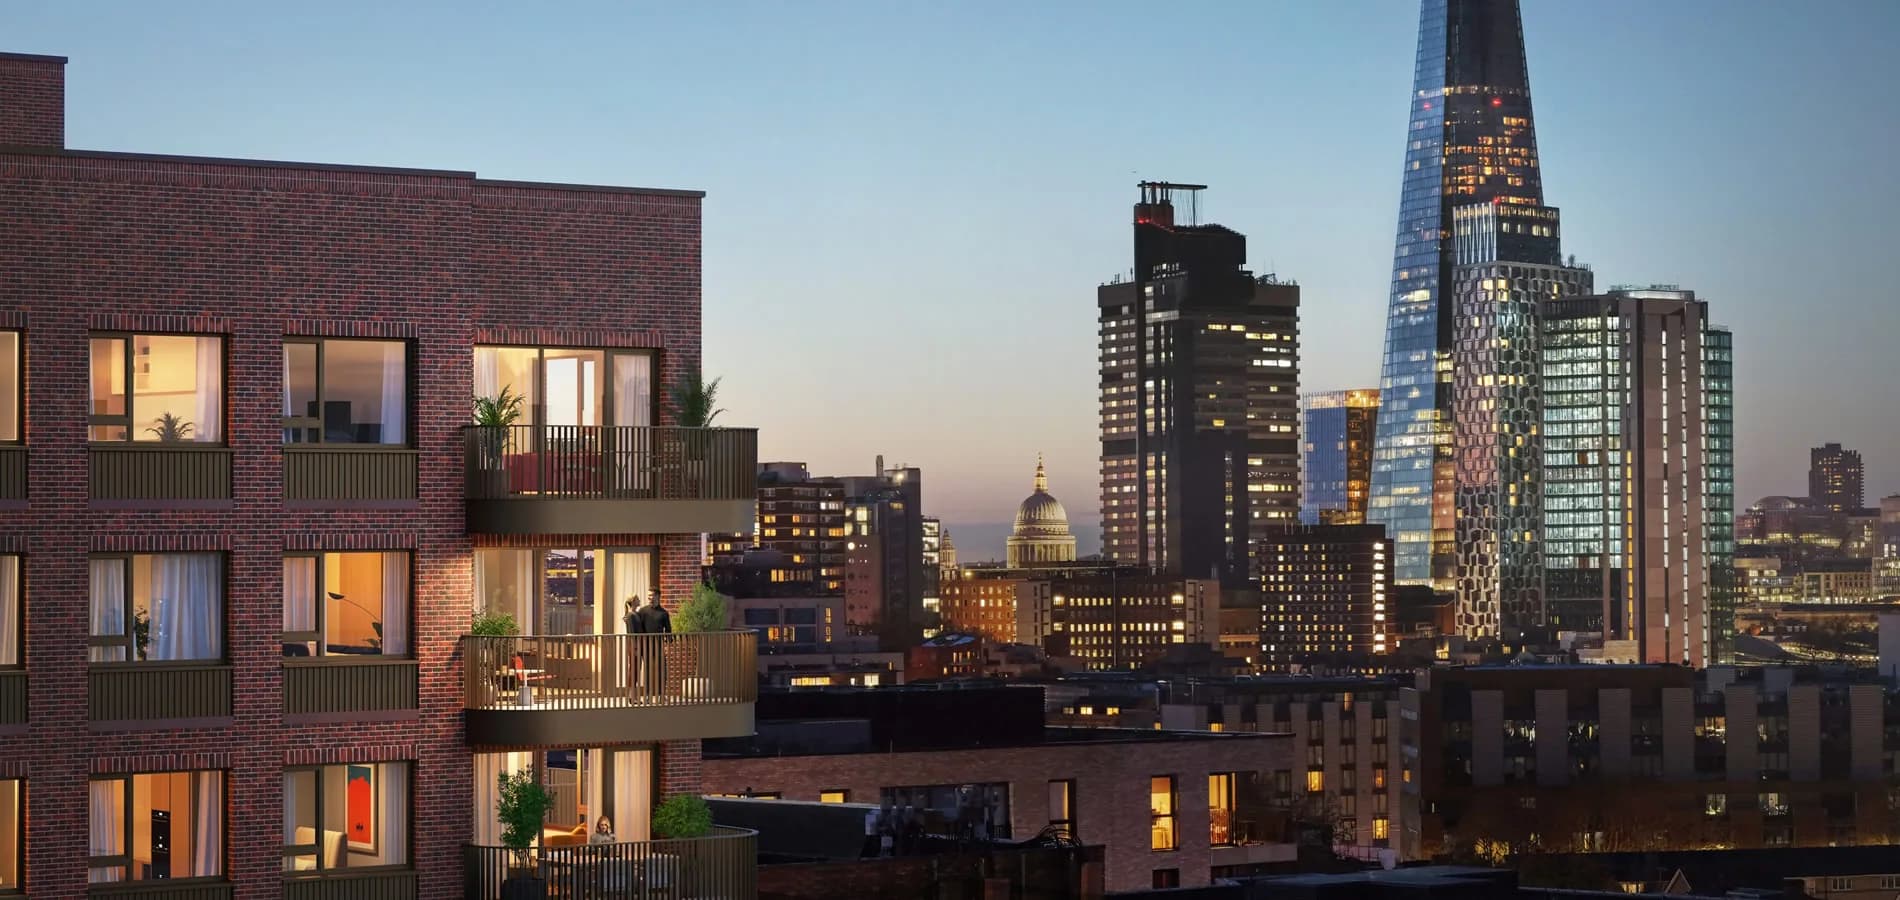
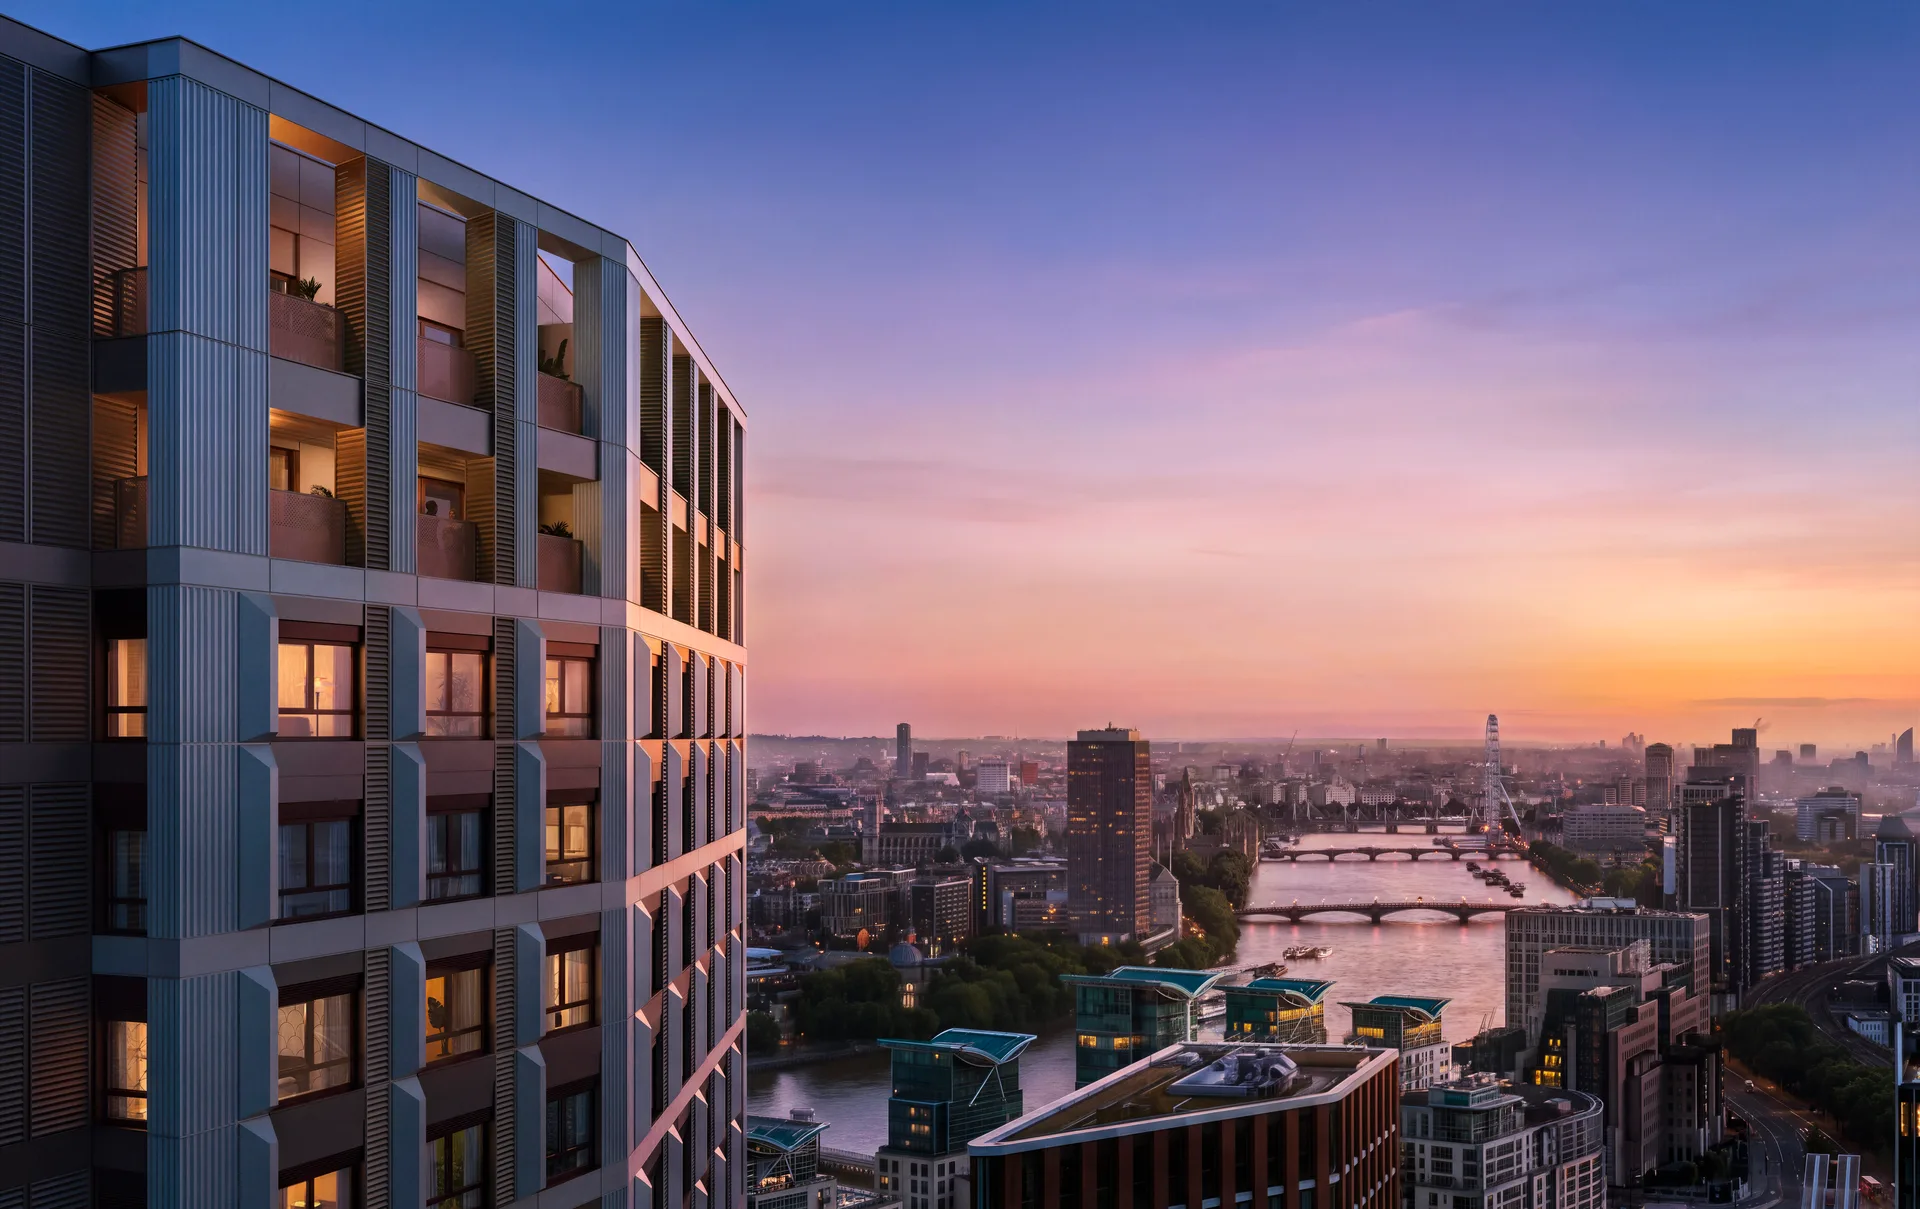
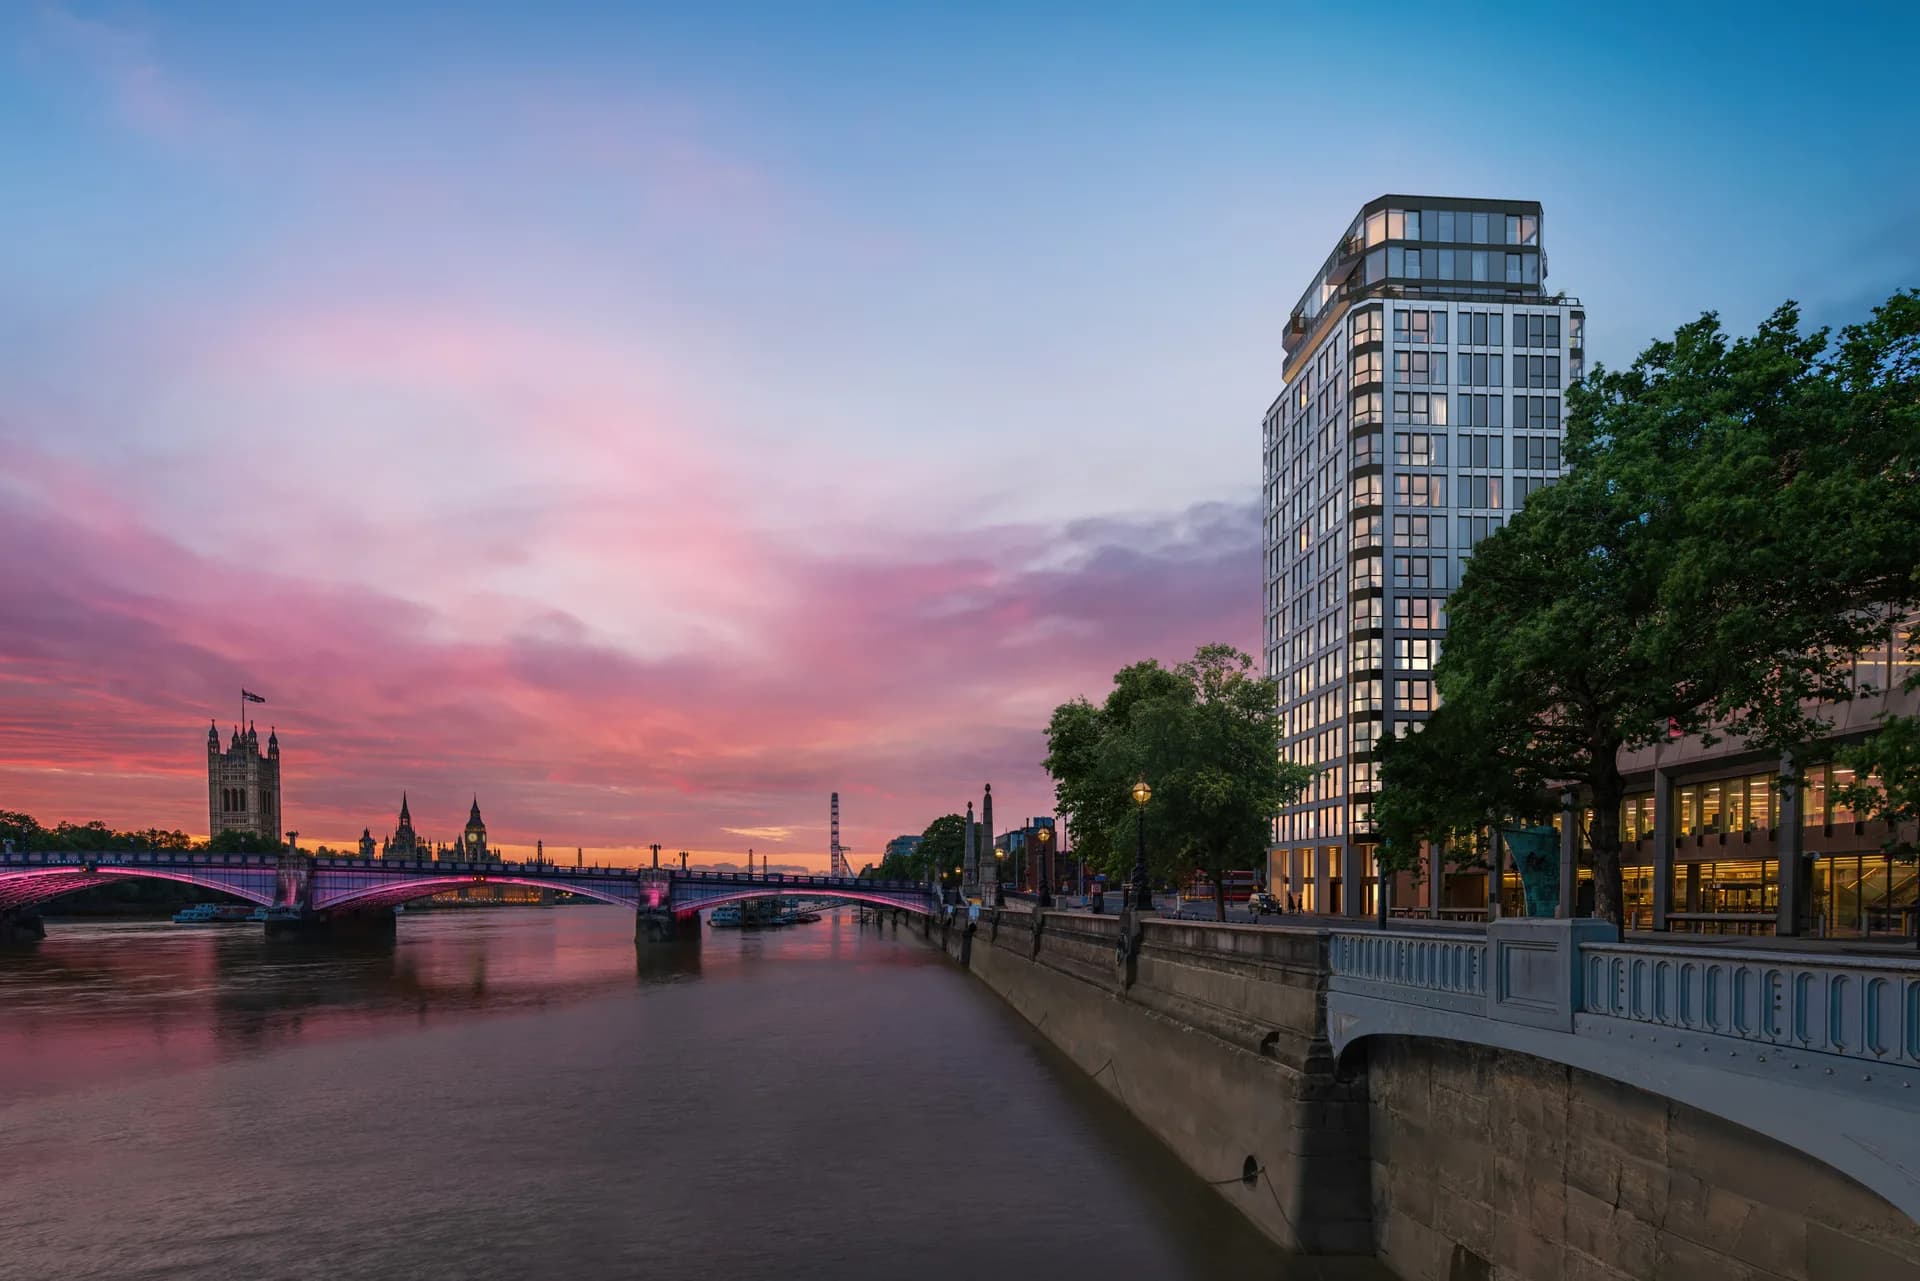
London developments for Nigerian investors
Tax & structure
UK-Nigeria: the tax and legal picture
Comprehensive double taxation treaty. Nigerian investors pay UK tax first on UK rental income and claim relief on Nigerian self-assessment where applicable.
SDLT
Standard residential + 5% investor surcharge + 2% non-resident surcharge. On a £400k purchase the combined SDLT is approximately £38,000.
UK income tax
UK income tax on rental profit at 20% and 40% in 2026/27, rising to 22% and 42% on property income from April 2027. The personal allowance (£12,570) is available to some non-residents, depending on nationality and treaty terms. Rent is paid gross only once HMRC approves you under the Non-Resident Landlord Scheme; otherwise the letting agent deducts 20%.
CGT on disposal
Non-resident CGT at 18% (basic) or 24% (higher). Nigeria-resident individuals declare the gain for treaty-based credit.
Naira hedging
UK property income received in GBP. Many Nigerian clients hold rent in UK accounts and repatriate selectively at favourable FX points rather than monthly.
Visa & residency
Owning UK property does not give a right to live in the UK. Nigerian citizens may qualify for routes such as Skilled Worker, Global Talent or, with a UK-born grandparent, UK Ancestry. Take immigration advice separately from the purchase.
General information, not tax, legal or immigration advice. UK rates are for the 2026/27 tax year unless stated, and this guide was last reviewed on . Take advice on your own circumstances before you act.
FX
NGN → GBP
The naira moved from roughly ₦550 to more than ₦2,000 to the pound between 2021 and 2024 after the Central Bank of Nigeria unified its exchange rates. Most investors convert to US dollars first through a domiciliary account, then from dollars to sterling through an international bank or currency broker.
How we adapt the process
How the purchase works from Nigeria
- Moving funds
- Funds must move through regulated banking channels with a clear paper trail. Most investors build up US dollars in a domiciliary account before converting. Take Nigerian tax and legal advice on the route that suits you.
- Source of funds documentation
- UK solicitors require comprehensive source-of-funds documentation for Nigerian-origin capital. Bank statements showing USD accumulation, business trading history, salary records, and prior UK transactions all accepted. Budget 4 to 6 weeks for thorough AML clearance.
- Meeting rhythm
- 9am UK / 10am Lagos works for most Nigerian clients. Early evening UK / late evening Lagos also common for diaspora with UK-based family.
- Remote signing
- Documents can be signed before a Nigerian notary public and authenticated for use in England. Your solicitor confirms the exact format before you sign.
FAQ
What Nigerian investors ask us most
How do I move funds from Nigeria to the UK legally given FX controls?
The usual route is to build up US dollars in a Nigerian domiciliary account, then convert dollars to sterling through an international bank or currency broker. Full source-of-funds documentation is needed at each step, and you should take Nigerian legal and tax advice before moving funds.
Can I get a UK mortgage as a Nigerian resident?
Yes, through specialist lenders. The choice is narrower than for some other countries, deposits of 35% to 40% are common, and lenders will want clear evidence of income and funds. We introduce you to a whole-of-market broker who arranges overseas-resident lending.
How does the UK-Nigeria tax treaty work in practice?
UK tax is paid first on UK rental income. A Nigerian-resident taxpayer then declares the income in Nigeria and claims credit for the UK tax paid. Under the Nigeria Tax Act 2025 the top personal rate is 25% from January 2026, so the UK tax paid will often cover any Nigerian liability. Your Nigerian adviser confirms the position.
What is the typical first purchase for a Nigerian client?
It depends on budget and goals. A city-centre apartment in Manchester or Birmingham is a common first purchase for income; London suits buyers focused on long-term capital value. On a first call we set out the options that fit.
Book a discovery call
Speak to a founder, in your time zone
Nigerian clients typically start with a 20-minute video call. We send three live investment options, the tax structure we would use, and an FX plan before our second meeting.
- No cost for the consultation
- No obligation after the call
- Calls scheduled in your local time
Also served
Other international markets we service
United Arab Emirates
AED · GMT+4 (GST)
The UAE levies no personal income tax, so for an individual investor UK rental income and gains are taxed once, in the UK, with no second charge at home.
South Africa
ZAR · GMT+2 (SAST)
The rand has weakened substantially against sterling over the past 15 years. For South African families, a sterling asset spreads wealth outside a single currency, and for many it sits alongside UK citizenship or ancestry ties.
Kuwait
KWD · GMT+3 (AST)
The Kuwaiti dinar is the world's highest-valued currency unit, and Kuwait levies no personal income tax. For an individual investor, UK tax is the only tax on UK rent and gains, and a sterling asset diversifies wealth otherwise held in the region.
Saudi Arabia
SAR · GMT+3 (AST)
Saudi Arabia does not levy personal income tax on individuals' salaries, so for most Saudi-based individual investors the UK tax on UK rent and gains is the main charge. The riyal is pegged to the US dollar, so the GBP cost of a purchase moves with sterling against the dollar.
Next Step
Ready to explore UK property from Nigeria?
Book a 20-minute discovery call. We will send three live investment options and the tax structure we would recommend for your profile before our second meeting.
Book a Free Consultation