🇿🇦 South African investors
UK property investment from South Africa.
A sterling asset alongside rand wealth. Exchange control allowances, the UK Ancestry route and the UK-South Africa tax treaty, explained for Johannesburg and Cape Town investors.
The Property Ombudsman
TPO D14716
ICO Registered
Ref ZB632945
Companies House No. 14716108
Est. England & Wales
Cavendish Square, W1
Central London office
Manchester office
Spinningfields, M1
Why now
Why South African investors are choosing UK property in 2026
The rand has weakened substantially against sterling over the past 15 years. For South African families, a sterling asset spreads wealth outside a single currency, and for many it sits alongside UK citizenship or ancestry ties.
Typical profile: £400k to £1.5m deployable. Dual-citizenship holders (many South Africans have UK passport rights via Ancestry). Mid-career professionals, emigration-adjacent, or wealth-preservation for families with multi-generational UK ties.
- 01
Rental income and capital held in sterling spread a family's wealth outside a single currency.
- 02
The UK is a leading destination for South African professionals, so family ties and a possible future move are in view for many buyers.
- 03
UK Ancestry visa route remains the most accessible settlement pathway for South African families with UK-born grandparents. Property purchase frequently accompanies relocation planning.
- 04
New-build homes in England come with a 10-year structural warranty, which suits an owner managing from abroad.
Where to buy
The UK cities South African investors most often consider
London
Central and riverside new-build with long leases and no ground rent. Lower yields than the regions, bought mainly for long-term capital value.
London market viewManchester
The largest regional rental market, with a deep city-centre tenant base drawn by finance, media and two major universities.
Manchester market viewBirmingham
The UK's second city, with major regeneration around the city centre and a large young workforce.
Birmingham market viewLive opportunities
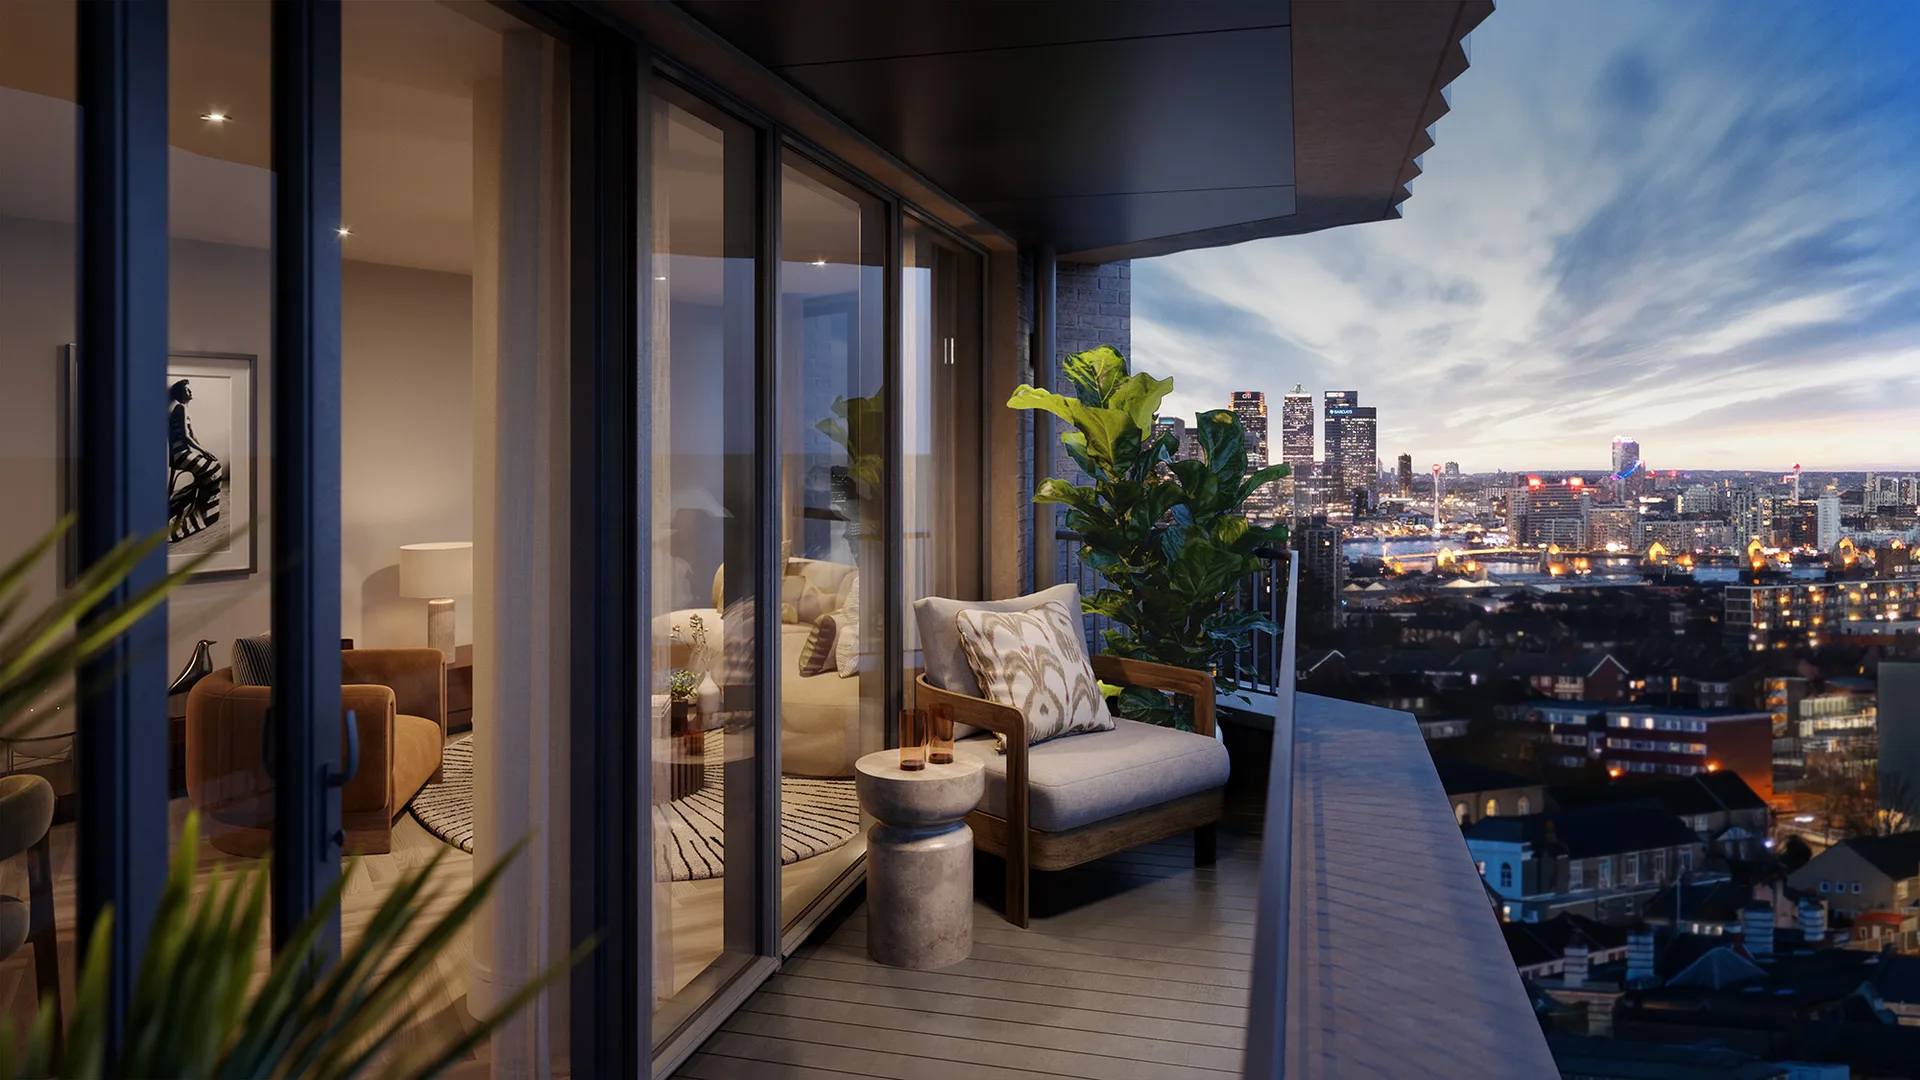
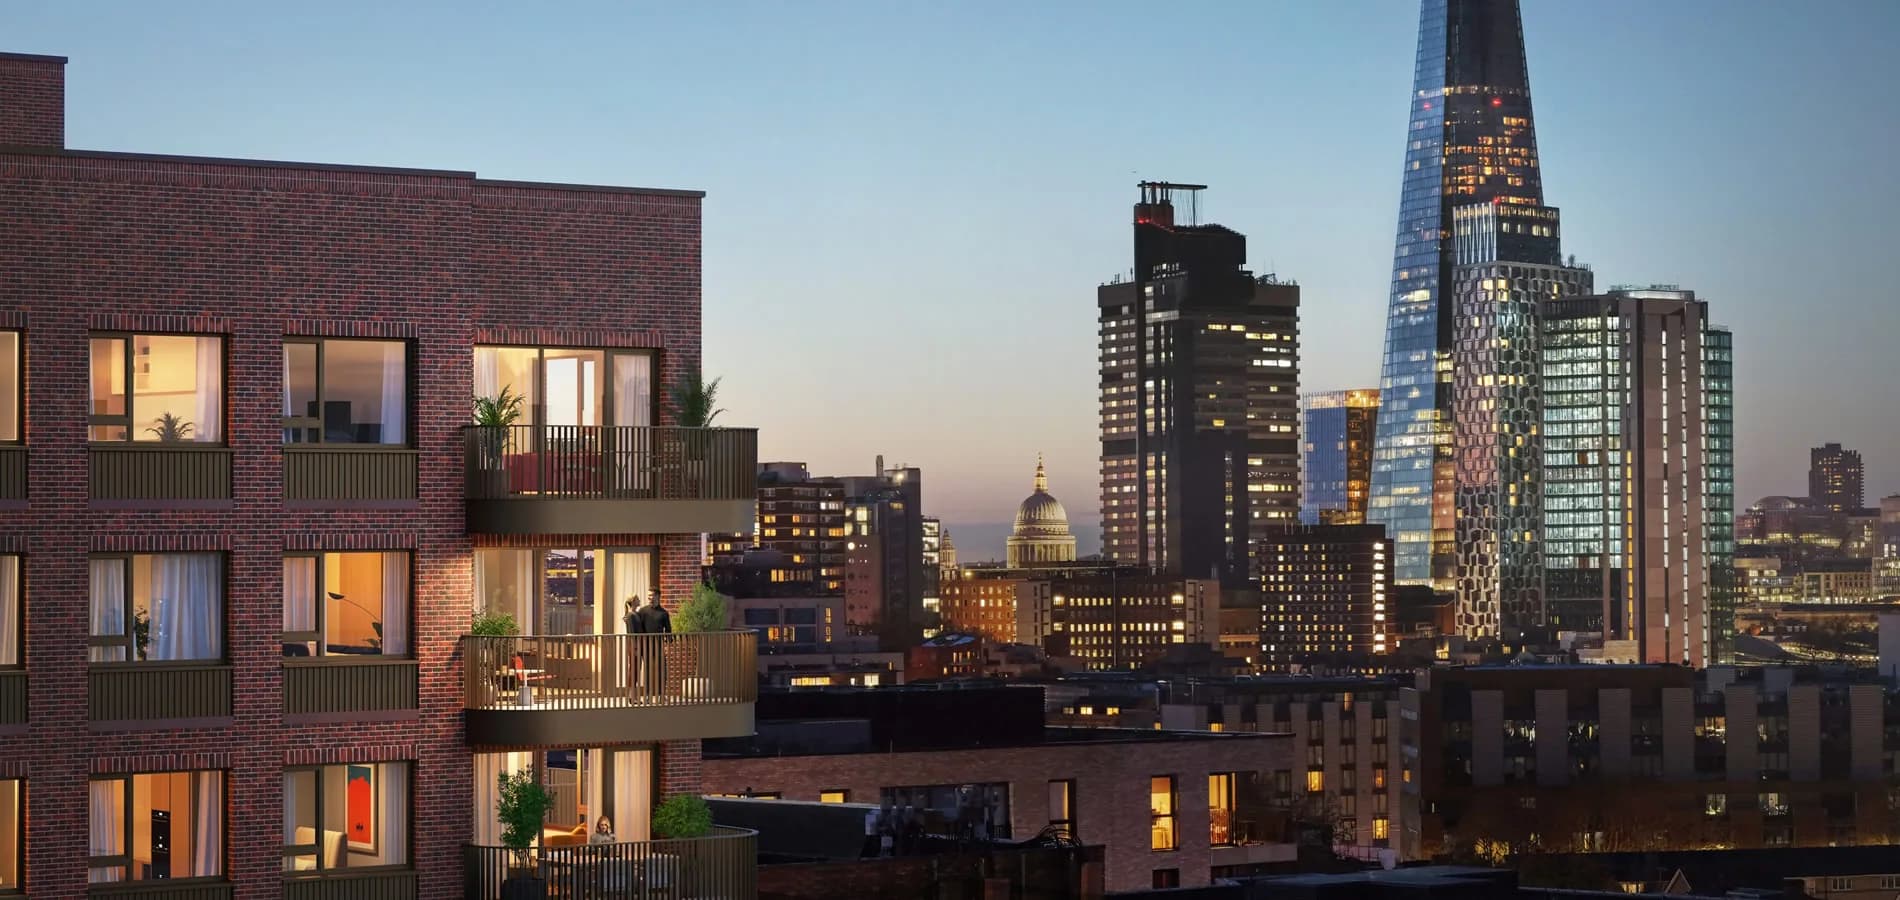
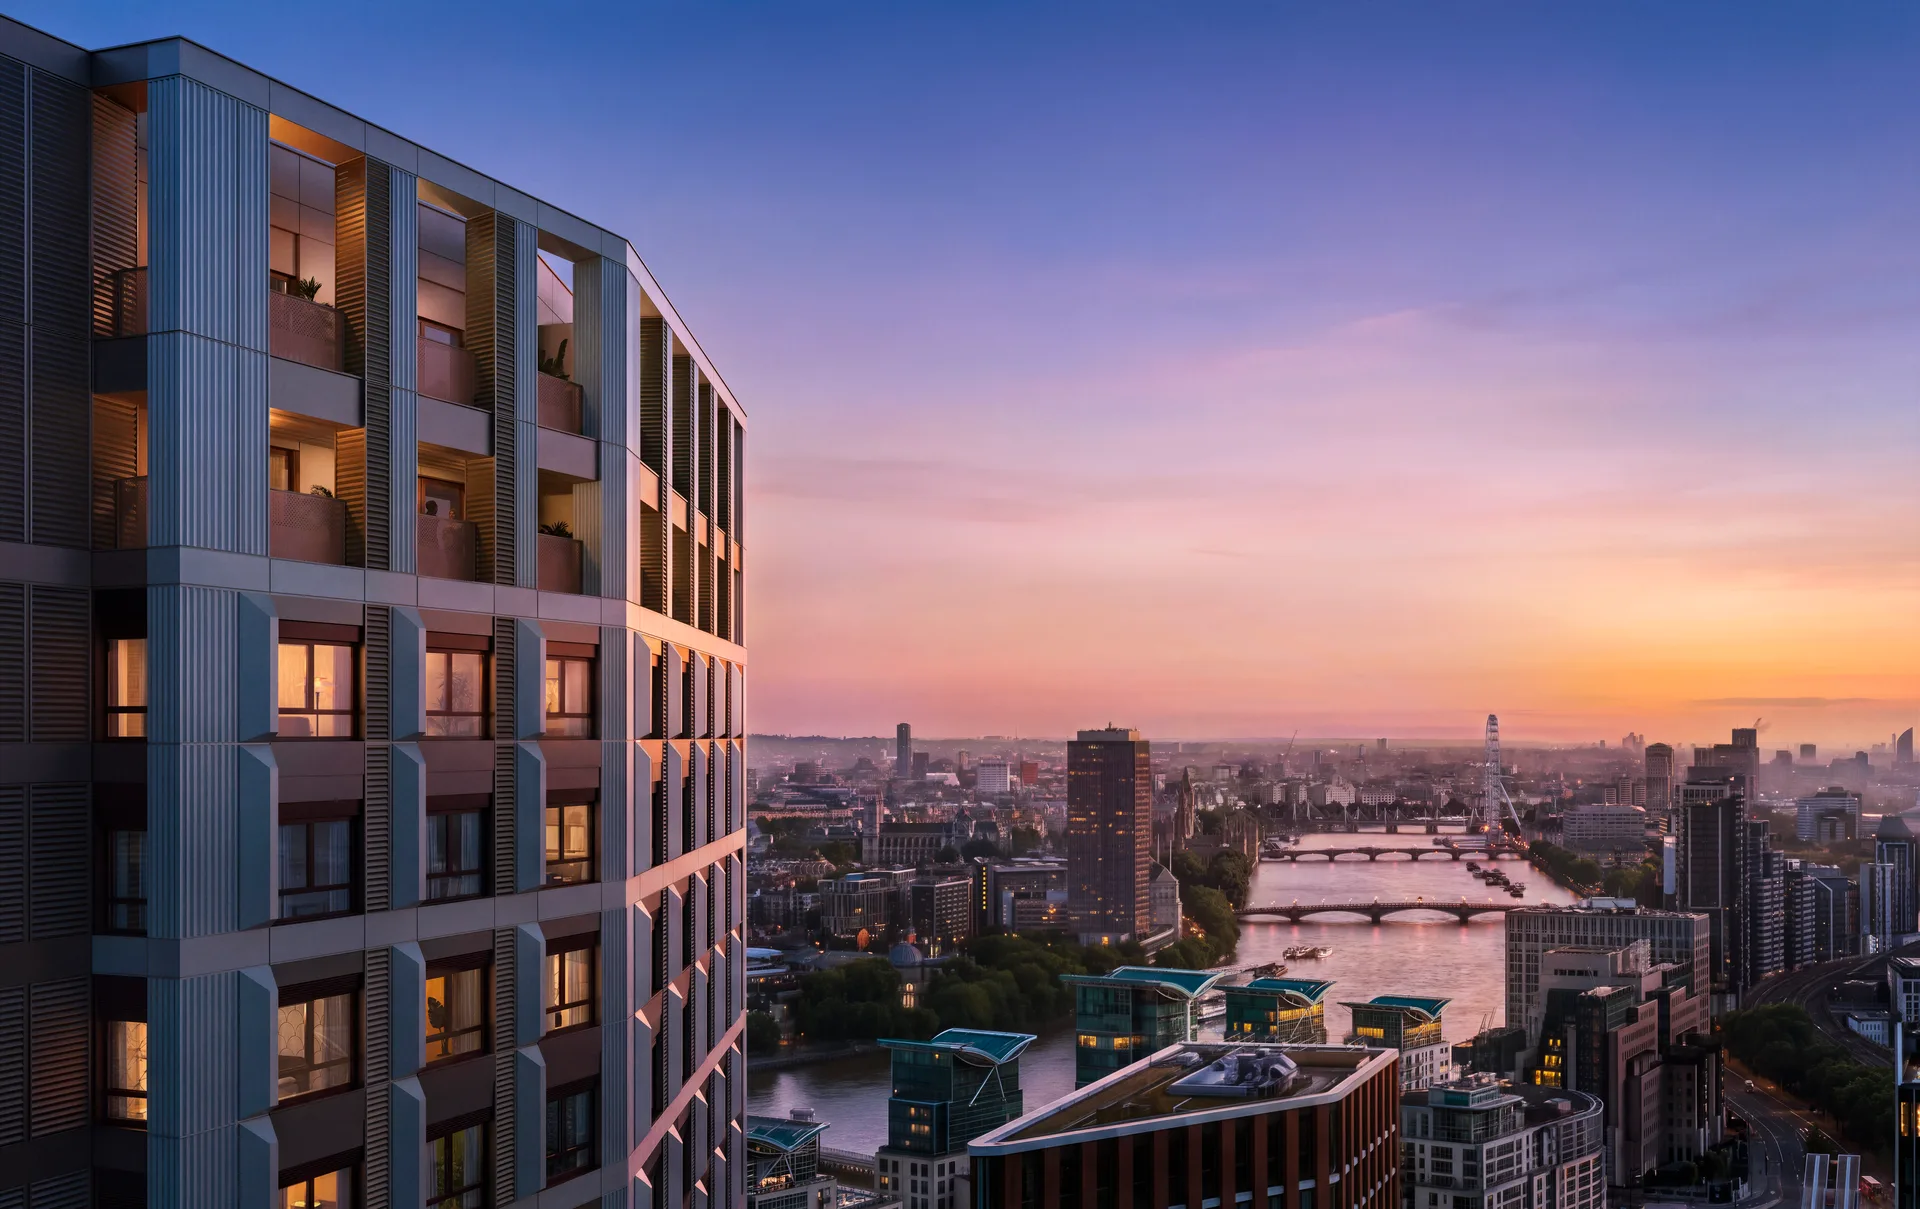
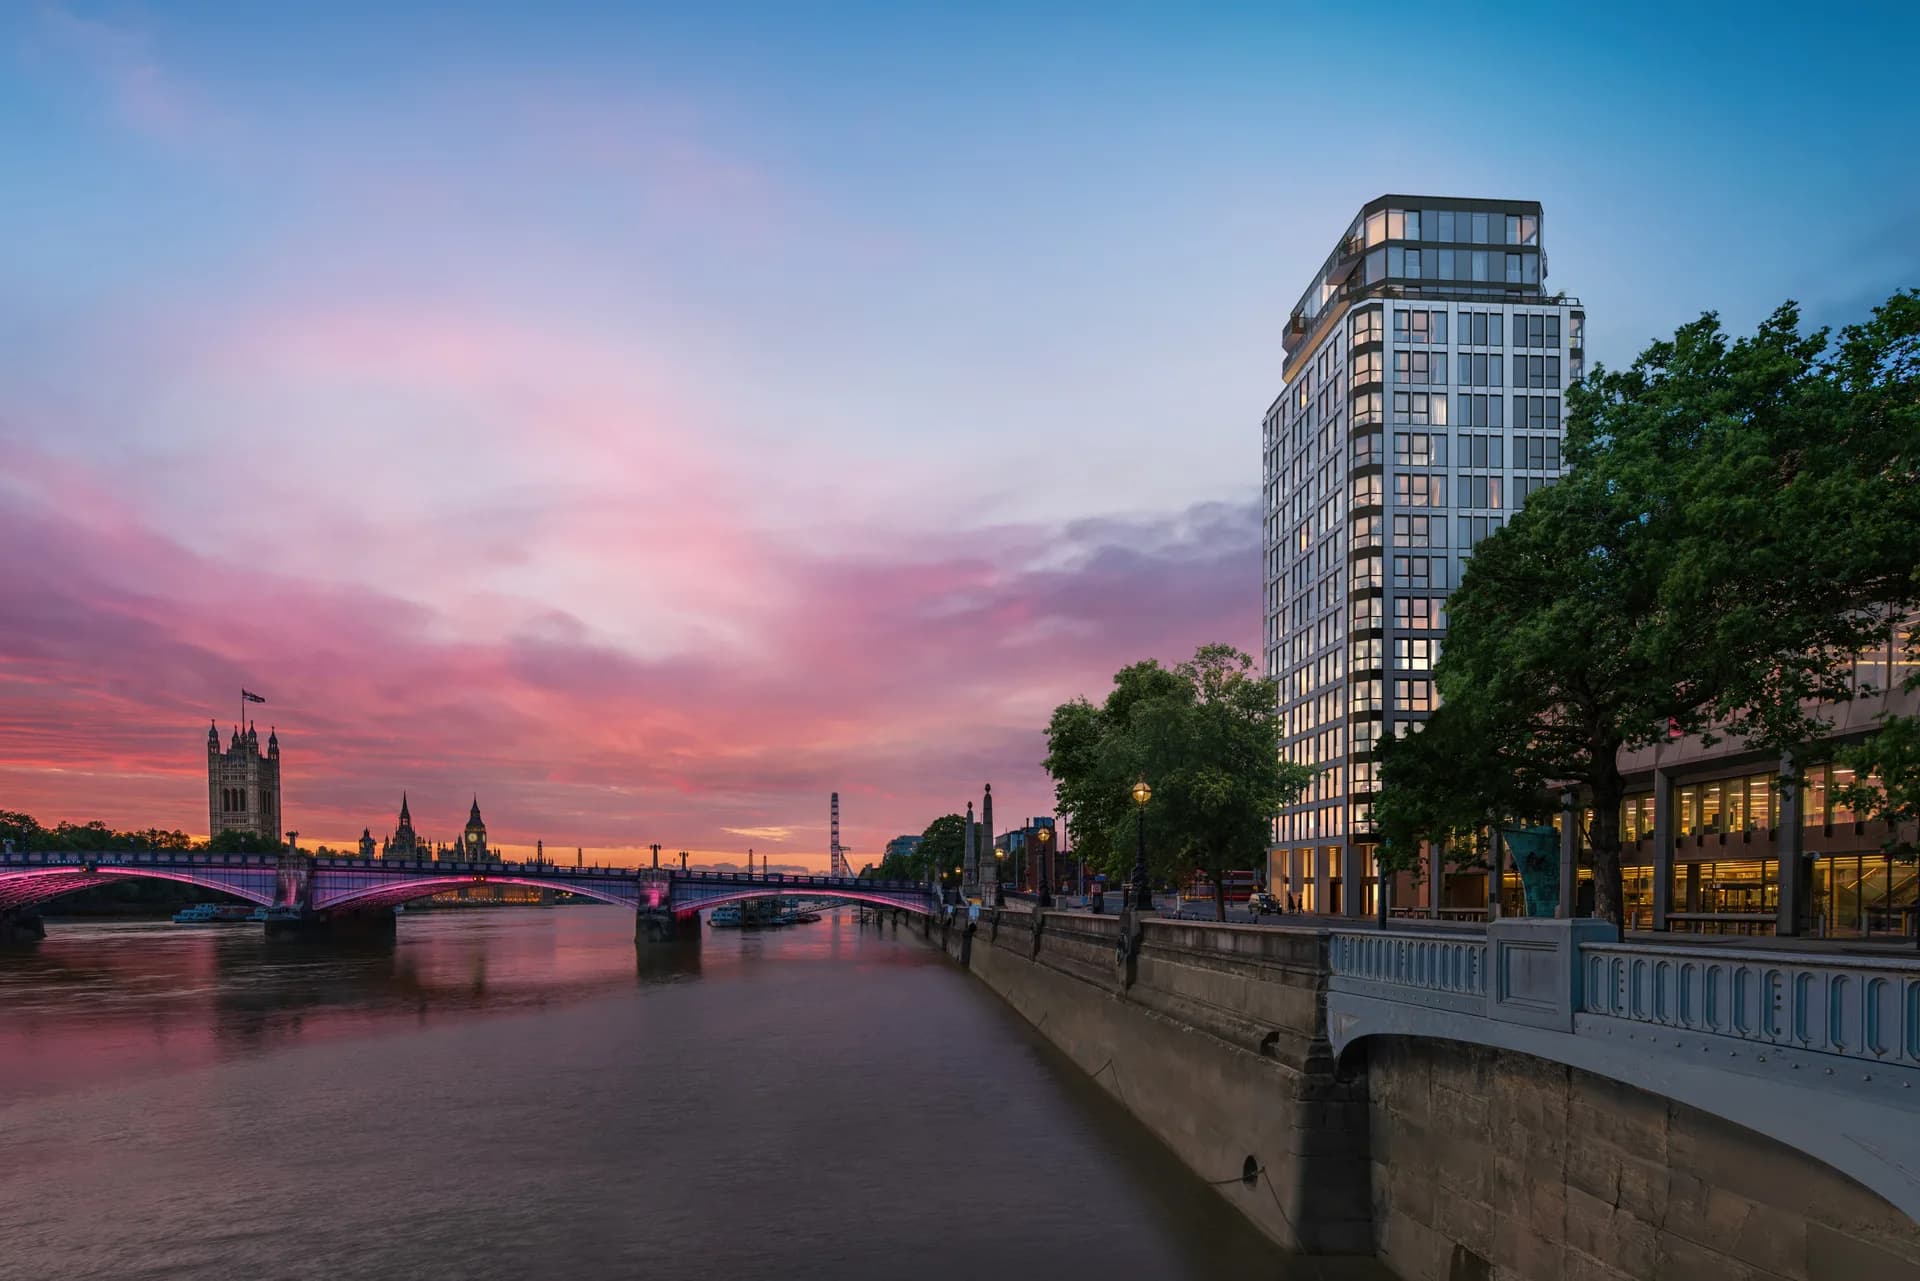
London developments for South African investors
Tax & structure
UK-South Africa: the tax and legal picture
Comprehensive double taxation treaty. South African residents pay UK tax first on UK-source income, then declare to SARS under Foreign Income rules and claim Foreign Tax Credit.
SDLT
Standard rates + 5% for an additional property + 2% for non-residents. The 2% surcharge turns on UK residence for SDLT, not nationality or visa: a buyer present in the UK for 183 days in the relevant 12-month window pays resident rates, and a refund can be claimed if the test is met within a year of completion.
UK + SARS tax
UK tax first (20/40%). Report to SARS annually via Foreign Income schedule. Foreign Tax Credit typically clears South African liability.
CGT on disposal
UK 18/24% plus South African CGT (effective rate approximately 18% for individuals after 40% inclusion rate times 45% marginal). Treaty provides relief.
Rand exchange control
Each adult has a single discretionary allowance of R1 million a year, plus a foreign investment allowance of up to R10 million a year with SARS approval. Larger purchases are often staged across tax years.
Visa & residency
Many South Africans with a UK-born grandparent qualify for the UK Ancestry visa, a five-year route to settlement. Owning property does not count towards it, but the timing of a move can affect stamp duty and mortgage options.
General information, not tax, legal or immigration advice. UK rates are for the 2026/27 tax year unless stated, and this guide was last reviewed on . Take advice on your own circumstances before you act.
FX
ZAR → GBP
The rand has traded between roughly R19 and R25 to the pound in recent years and moves with commodity prices and domestic news. Transfers run within your SARB allowances. A specialist currency broker will usually beat a retail bank rate on a transfer of this size, and a forward contract can fix the rate for an off-plan completion date.
How we adapt the process
How the purchase works from South Africa
- SARB exchange control
- We plan the purchase around your R1 million and R10 million allowances, staging larger acquisitions across tax years or funding them from capital already held offshore.
- Ancestry visa integration
- For clients planning UK relocation via Ancestry visa, we align property completion timing with UK residence establishment so resident SDLT and mortgage rates apply where possible.
- Meeting rhythm
- 1pm UK / 3pm SAST works for most South African clients. Many prefer morning calls UK / early afternoon South Africa.
- Remote signing
- Documents can be signed before a South African notary and apostilled for use in England. Your solicitor confirms the exact format before you sign.
FAQ
What South African investors ask us most
How does SARB exchange control affect my UK property purchase?
Each adult can move R1 million a year under the single discretionary allowance without SARS approval, plus up to R10 million a year under the foreign investment allowance with SARS approval. A couple can therefore move up to R22 million a year. Larger purchases can be staged across tax years.
I am eligible for UK Ancestry visa, should I get it before buying?
It depends on when you plan to move. The visa itself does not remove the 2% non-resident surcharge; UK residence for SDLT does. If you will be in the UK for 183 days in the relevant 12-month window, resident rates apply (a saving of £8,000 on a £400,000 purchase) and lenders may offer resident terms. We coordinate the timing with your immigration adviser.
What is the typical South African investor profile?
Two profiles are common: professionals buying a London or Manchester apartment as diversification and a possible future home, and families building a small UK portfolio as part of long-term estate planning.
How does SARS treat UK rental income?
South African tax residents declare UK rental income on their annual SARS return as foreign income. UK tax paid is creditable against South African liability. Because South African marginal rates (45% top) exceed UK non-resident higher rate (40%), most high-income South African investors pay some residual SARS top-up tax.
Book a discovery call
Speak to a founder, in your time zone
South African clients typically start with a 20-minute video call. We send three live investment options, the tax structure we would use, and an FX plan before our second meeting.
- No cost for the consultation
- No obligation after the call
- Calls scheduled in your local time
Also served
Other international markets we service
United Arab Emirates
AED · GMT+4 (GST)
The UAE levies no personal income tax, so for an individual investor UK rental income and gains are taxed once, in the UK, with no second charge at home.
Nigeria
NGN · GMT+1 (WAT)
For a Nigerian investor, UK property is a store of value in sterling. The naira has fallen sharply against the pound since the 2023 currency reforms, so assets held in sterling have protected purchasing power in a way naira assets have not.
Kuwait
KWD · GMT+3 (AST)
The Kuwaiti dinar is the world's highest-valued currency unit, and Kuwait levies no personal income tax. For an individual investor, UK tax is the only tax on UK rent and gains, and a sterling asset diversifies wealth otherwise held in the region.
Saudi Arabia
SAR · GMT+3 (AST)
Saudi Arabia does not levy personal income tax on individuals' salaries, so for most Saudi-based individual investors the UK tax on UK rent and gains is the main charge. The riyal is pegged to the US dollar, so the GBP cost of a purchase moves with sterling against the dollar.
Next Step
Ready to explore UK property from South Africa?
Book a 20-minute discovery call. We will send three live investment options and the tax structure we would recommend for your profile before our second meeting.
Book a Free Consultation