🇸🇬 Singapore investors
UK property investment from Singapore.
Lower stamp duty than at home, rent usually taxed only in the UK, and a second property market to spread risk. A guide for Singapore-based investors.
The Property Ombudsman
TPO D14716
ICO Registered
Ref ZB632945
Companies House No. 14716108
Est. England & Wales
Cavendish Square, W1
Central London office
Manchester office
Spinningfields, M1
Why now
Why Singapore investors are choosing UK property in 2026
Singapore charges foreigners 60% Additional Buyer's Stamp Duty on residential property, and citizens 20% on a second home. Against that, the UK's surcharges on an overseas buyer (5% for an additional property plus 2% for non-residents) are modest.
Typical profile: £300k to £1.5m deployable, often cash or low-LTV (40-50%), diversification from an already-concentrated Singapore property portfolio.
- 01
A UK holding spreads a Singapore investor's property exposure across a second, separately priced market.
- 02
For most Singapore-resident individuals, UK rent is taxed only in the UK.
- 03
Gross rental yields in UK regional cities are generally higher than on Singapore private residential property.
- 04
A second Singapore home costs a citizen 20% ABSD and a foreigner 60%. The UK charges an overseas buyer 7% on top of standard rates.
Where to buy
The UK cities Singapore investors most often consider
London
Central and riverside new-build with long leases and no ground rent. Lower yields than the regions, bought mainly for long-term capital value.
London market viewManchester
The largest regional rental market, with a deep city-centre tenant base drawn by finance, media and two major universities.
Manchester market viewBirmingham
The UK's second city, with major regeneration around the city centre and a large young workforce.
Birmingham market viewLive opportunities
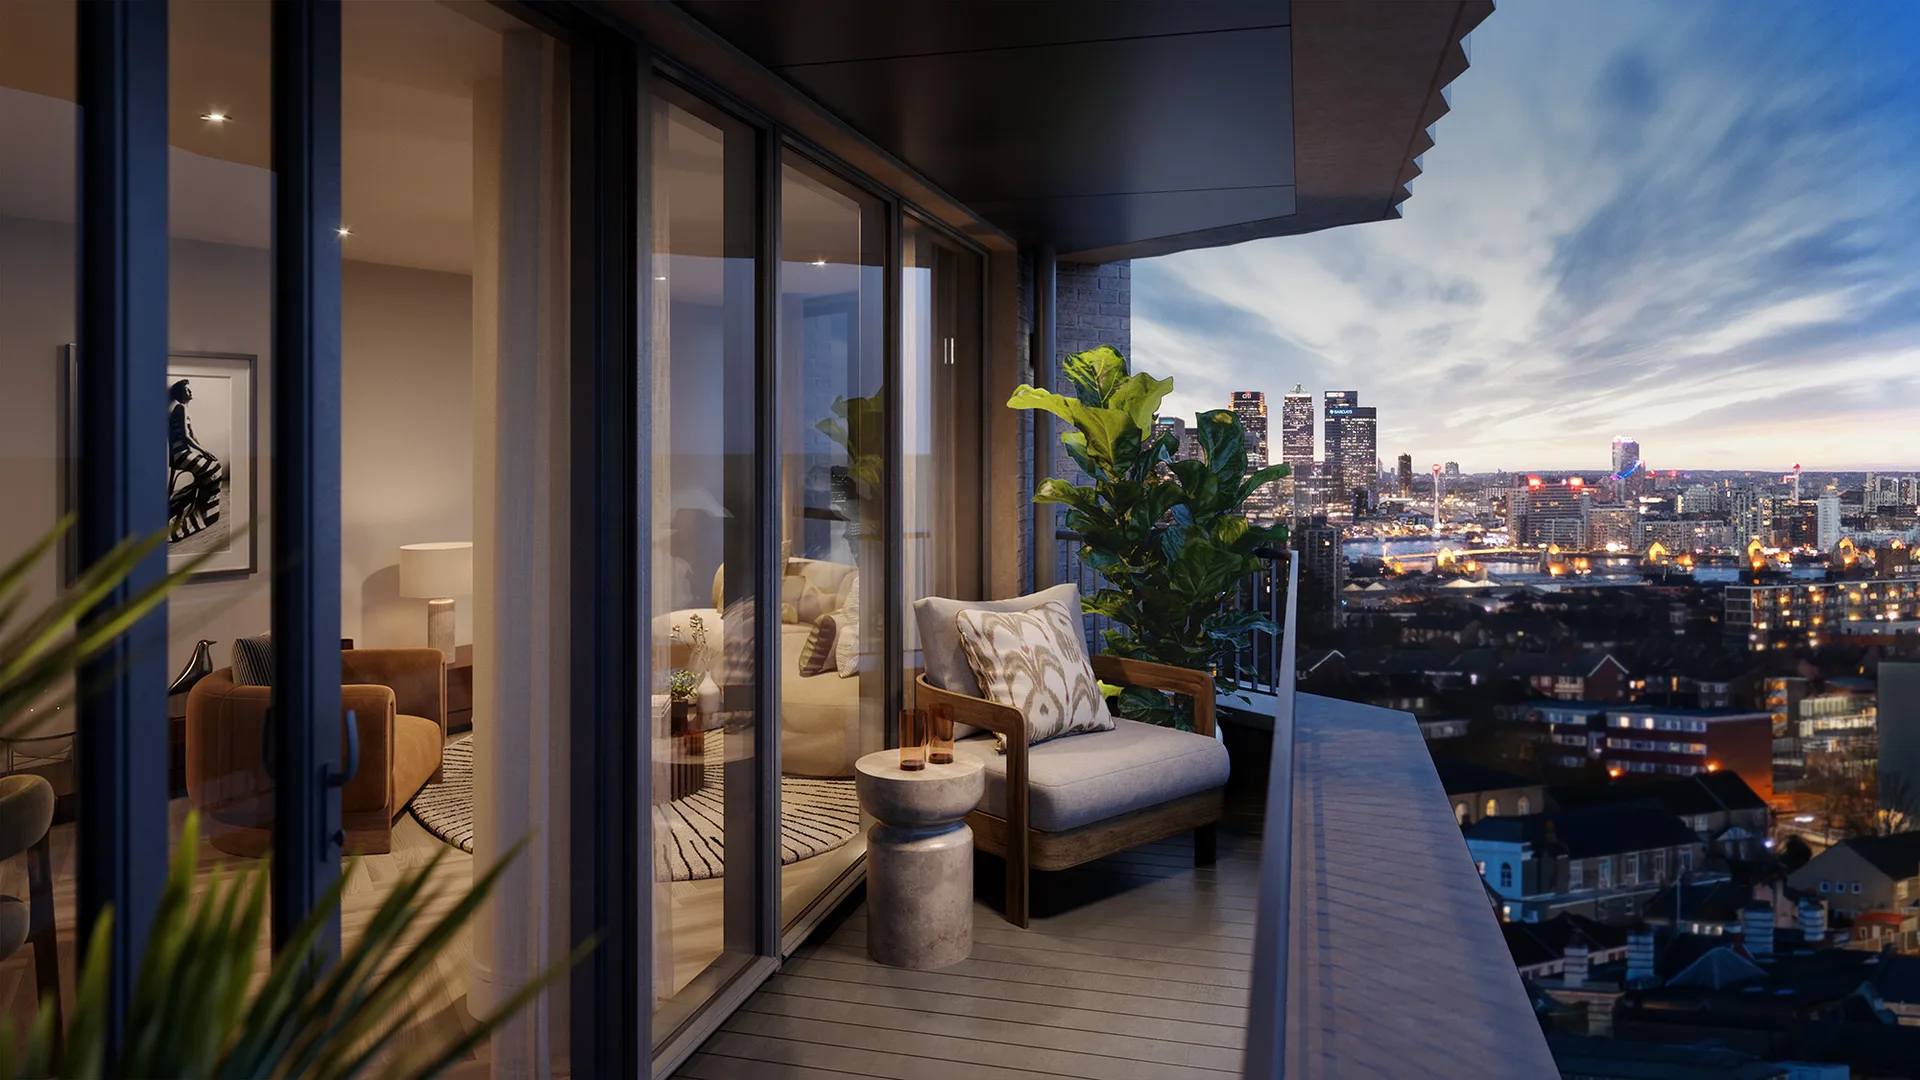
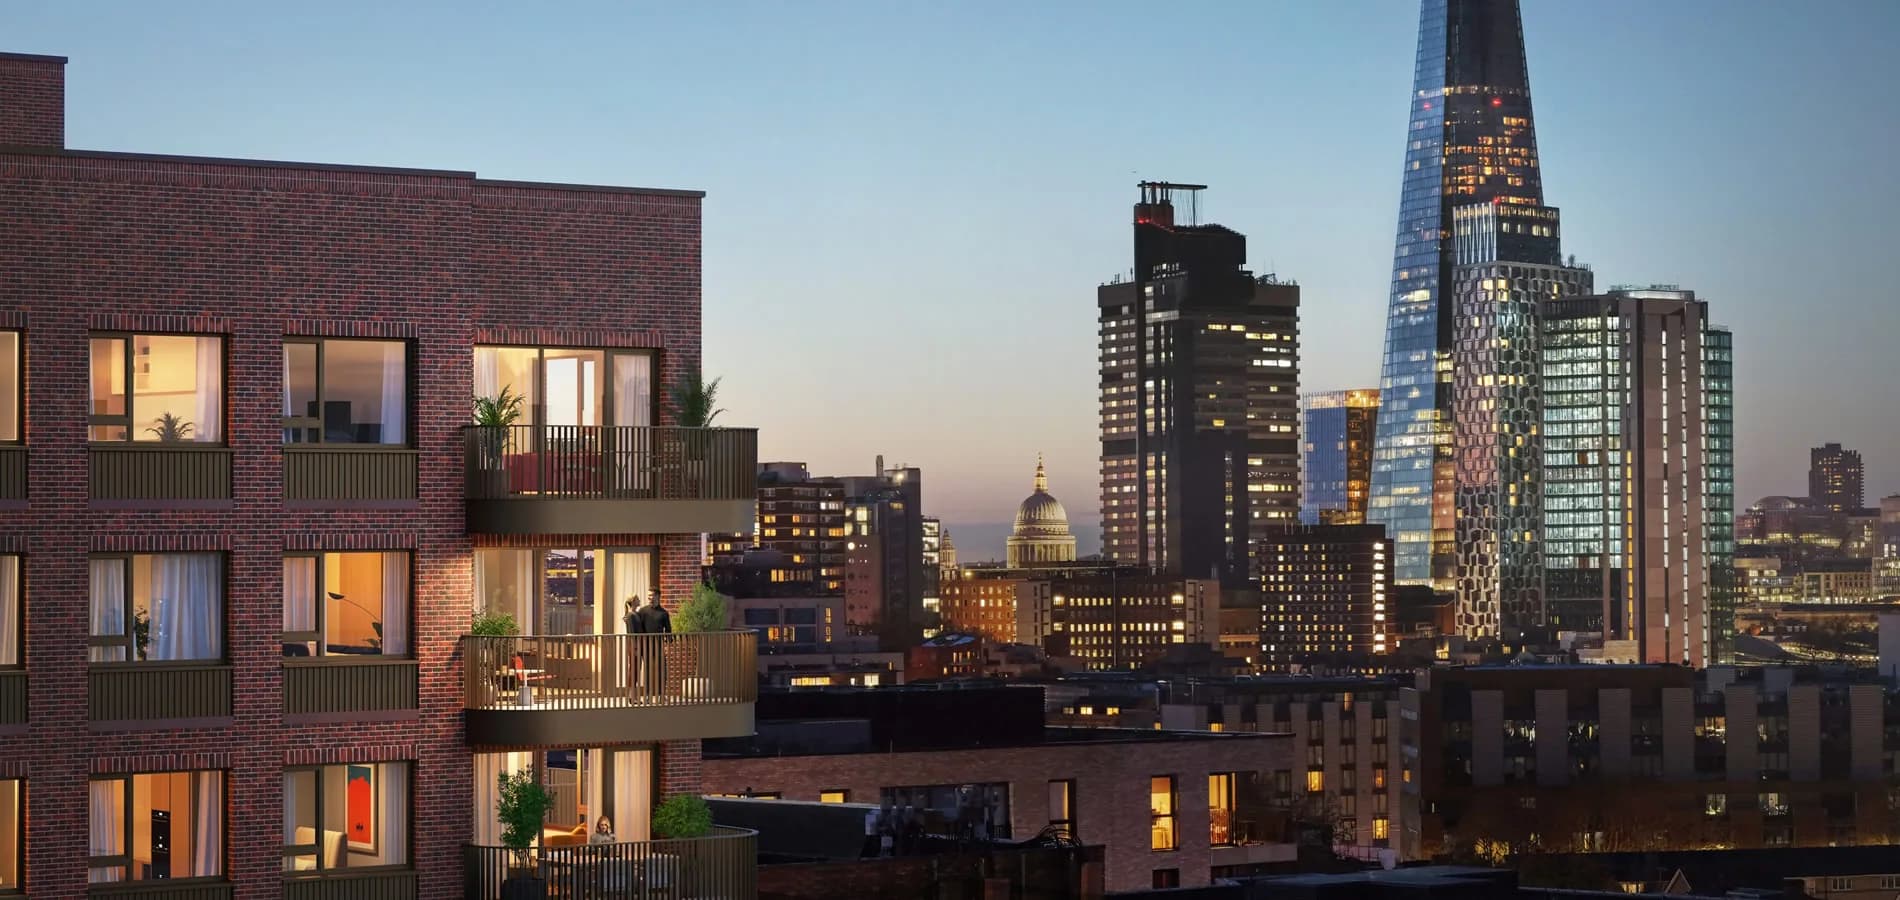
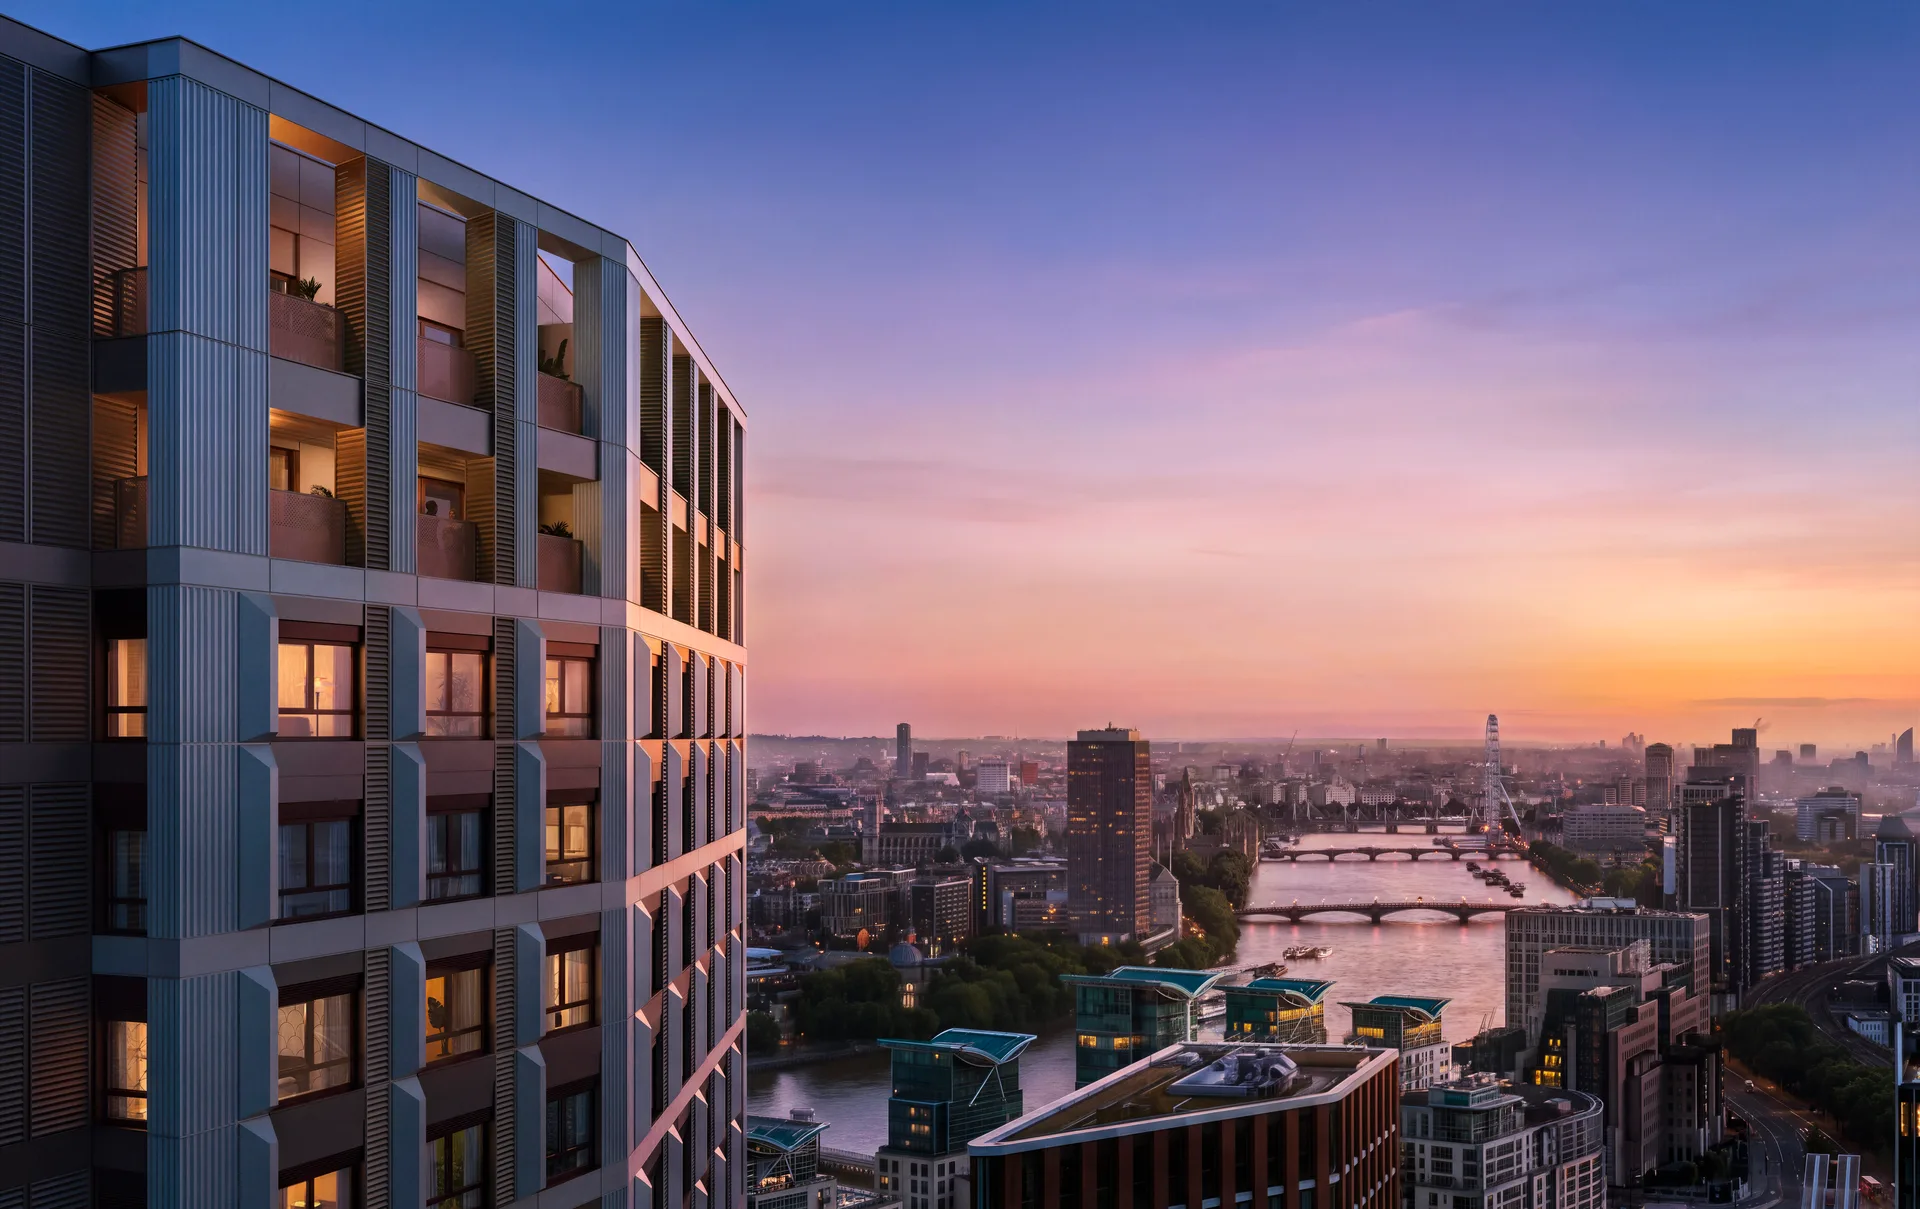
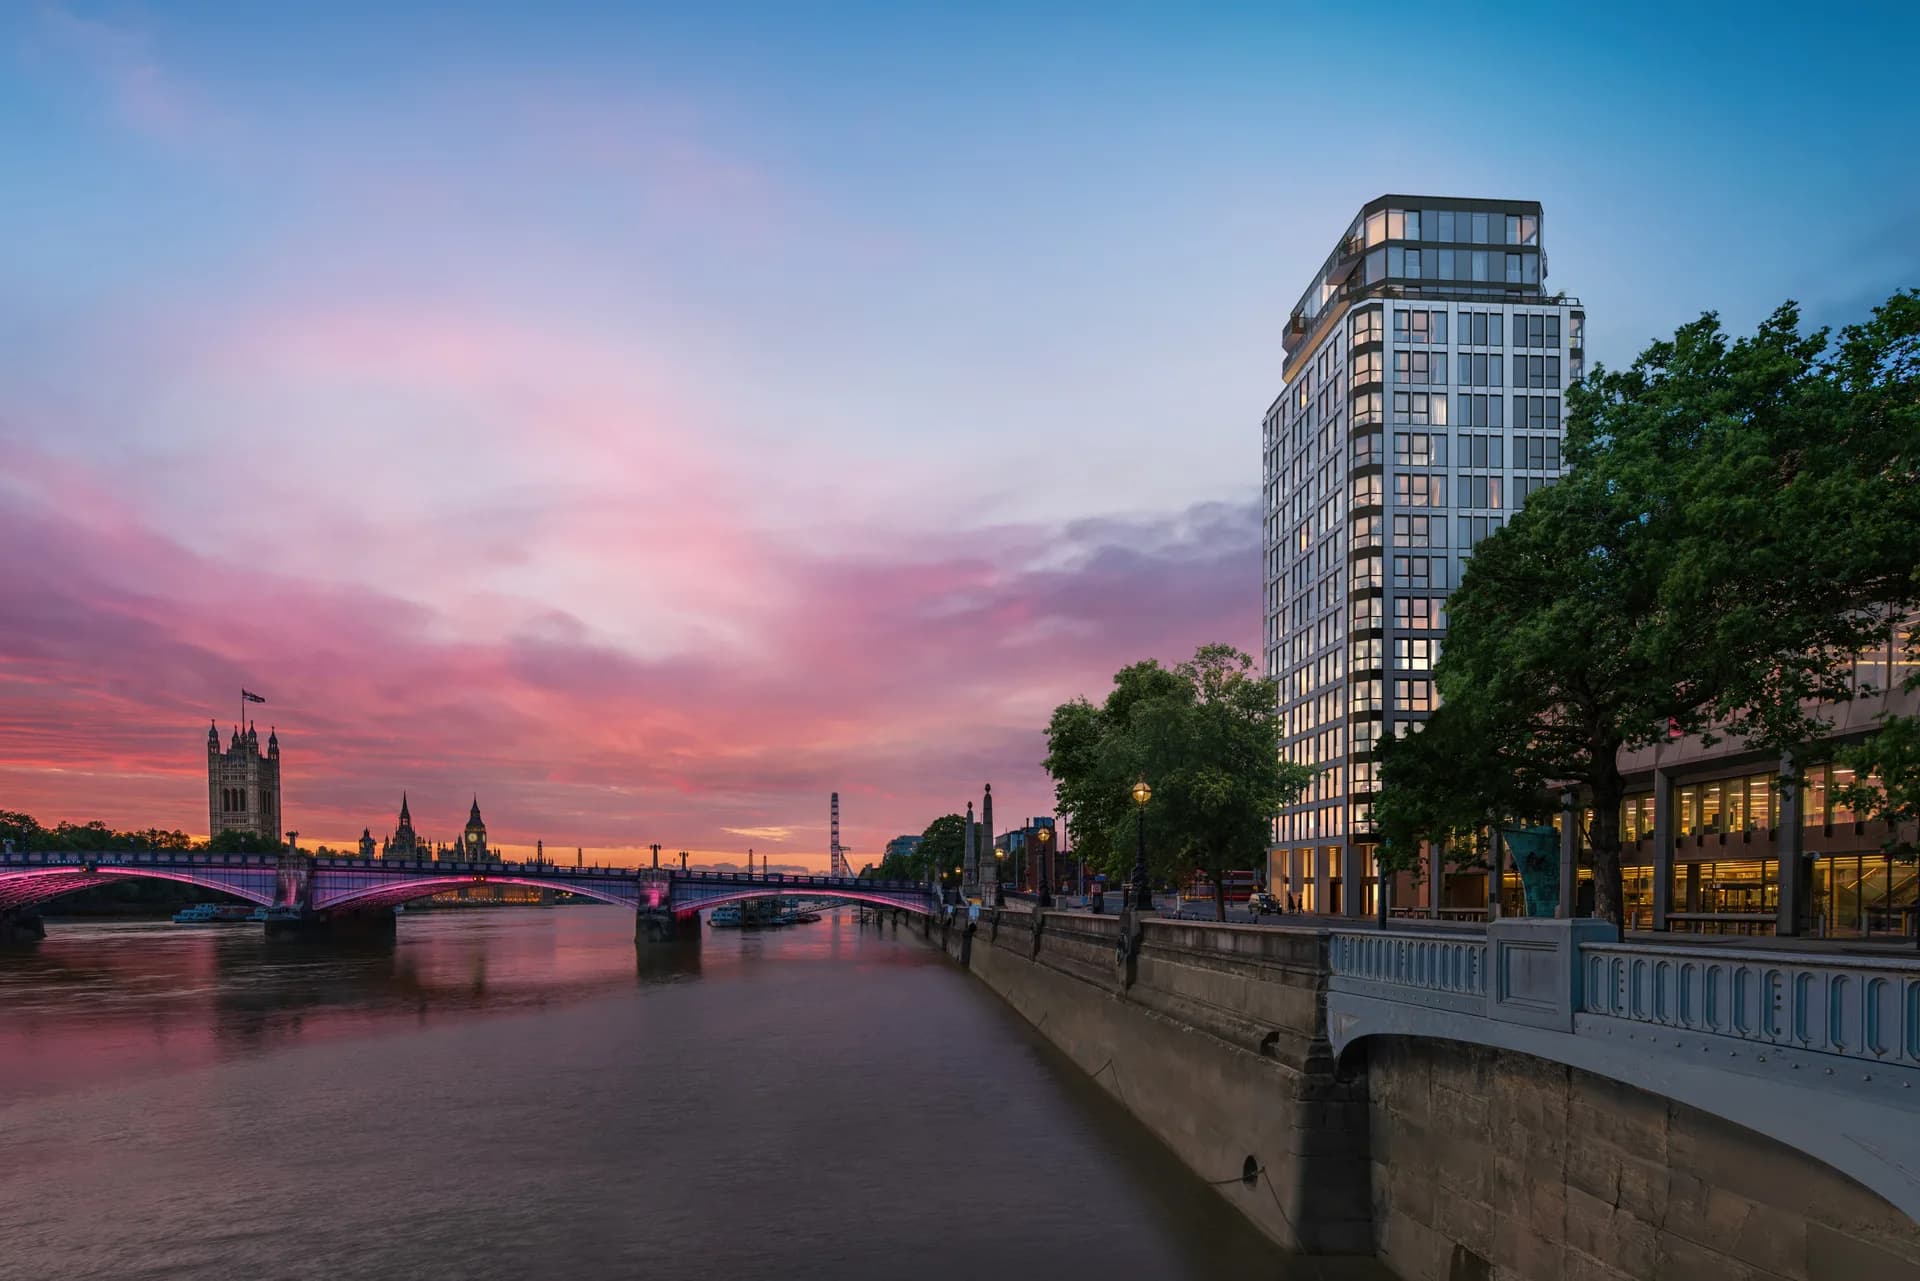
London developments for Singapore investors
Tax & structure
UK-Singapore: the tax and legal picture
Comprehensive double taxation treaty. Foreign-sourced income received by Singapore-resident individuals is generally exempt from Singapore tax, so for most individual investors UK tax is the only tax on UK rent.
SDLT
Standard rates + 5% for an additional property + 2% for non-residents. Far lower than the 60% ABSD a foreigner pays in Singapore.
UK income tax
UK income tax on rental profit at 20% and 40% in 2026/27, rising to 22% and 42% on property income from April 2027. The personal allowance (£12,570) is available to some non-residents, depending on nationality and treaty terms. Rent is paid gross only once HMRC approves you under the Non-Resident Landlord Scheme; otherwise the letting agent deducts 20%.
CGT
UK CGT applies on disposal for non-residents: 18% or 24%. Singapore imposes no CGT domestically, so UK charge is the only tax cost.
SRS and CPF
CPF savings cannot be used to buy overseas property, and Supplementary Retirement Scheme funds cannot be used to buy property directly. Purchases are funded from personal or investment capital.
Visa & residency
Owning UK property does not give a right to live in the UK. If relocation is in view, routes such as Skilled Worker, Global Talent or Innovator Founder are the relevant ones. The Tier 1 Investor visa closed in 2022.
General information, not tax, legal or immigration advice. UK rates are for the 2026/27 tax year unless stated, and this guide was last reviewed on . Take advice on your own circumstances before you act.
FX
SGD → GBP
The Singapore dollar is managed against a basket of currencies by the Monetary Authority of Singapore, which tends to keep it steady. A specialist currency broker will usually beat a retail bank rate on a transfer of this size, and a forward contract can fix the rate for an off-plan completion date.
How we adapt the process
How the purchase works from Singapore
- Meeting rhythm
- Most Singapore clients prefer 8am-10am UK time (3pm-5pm SGT). Convenient for end-of-day Singapore conversations.
- Remote signing
- Documents can be signed before a Singapore notary public and apostilled by the Singapore Academy of Law. Your solicitor confirms the exact format before you sign.
- Identification
- Singapore NRIC or passport plus proof of residential address. CDD documentation standard.
- Banking and FX
- Several Singapore banks offer multi-currency accounts that can hold sterling, which is a simple way to keep a reserve for service charges and other UK costs.
FAQ
What Singapore investors ask us most
Can I use CPF to buy UK property?
No. CPF savings cannot be used for overseas property, and SRS funds cannot be used to buy property directly. UK purchases are funded from personal savings, investment accounts or a UK mortgage.
How does the UK-Singapore tax treaty work in practice?
You pay UK tax on UK rental income. Foreign-sourced income received by a Singapore-resident individual is generally exempt from Singapore tax, so in most cases there is nothing further to pay in Singapore. Income received through a partnership or company can be treated differently, so check with your adviser.
Is it worth considering offshore holding structures?
Rarely optimal post-2019. Non-resident CGT rules and the abolition of most stamp-duty avoidance mean simple structures (direct personal name or UK SPV) are usually cleanest.
What is the typical deal flow for Singapore clients?
London and central Manchester are the most common starting points. Many investors begin with one apartment and add a second once they have seen the remote process and the lettings work in practice.
Book a discovery call
Speak to a founder, in your time zone
Singapore clients typically start with a 20-minute video call. We send three live investment options, the tax structure we would use, and an FX plan before our second meeting.
- No cost for the consultation
- No obligation after the call
- Calls scheduled in your local time
Also served
Other international markets we service
United Arab Emirates
AED · GMT+4 (GST)
The UAE levies no personal income tax, so for an individual investor UK rental income and gains are taxed once, in the UK, with no second charge at home.
Nigeria
NGN · GMT+1 (WAT)
For a Nigerian investor, UK property is a store of value in sterling. The naira has fallen sharply against the pound since the 2023 currency reforms, so assets held in sterling have protected purchasing power in a way naira assets have not.
South Africa
ZAR · GMT+2 (SAST)
The rand has weakened substantially against sterling over the past 15 years. For South African families, a sterling asset spreads wealth outside a single currency, and for many it sits alongside UK citizenship or ancestry ties.
Kuwait
KWD · GMT+3 (AST)
The Kuwaiti dinar is the world's highest-valued currency unit, and Kuwait levies no personal income tax. For an individual investor, UK tax is the only tax on UK rent and gains, and a sterling asset diversifies wealth otherwise held in the region.
Next Step
Ready to explore UK property from Singapore?
Book a 20-minute discovery call. We will send three live investment options and the tax structure we would recommend for your profile before our second meeting.
Book a Free Consultation